The Flatiron Review: Freehold Offices in Daun Penh
Meridian's 41-storey landmark sells what most foreigners don't know they can own: freehold strata offices, plus Ascott-run hotel units. The income read.
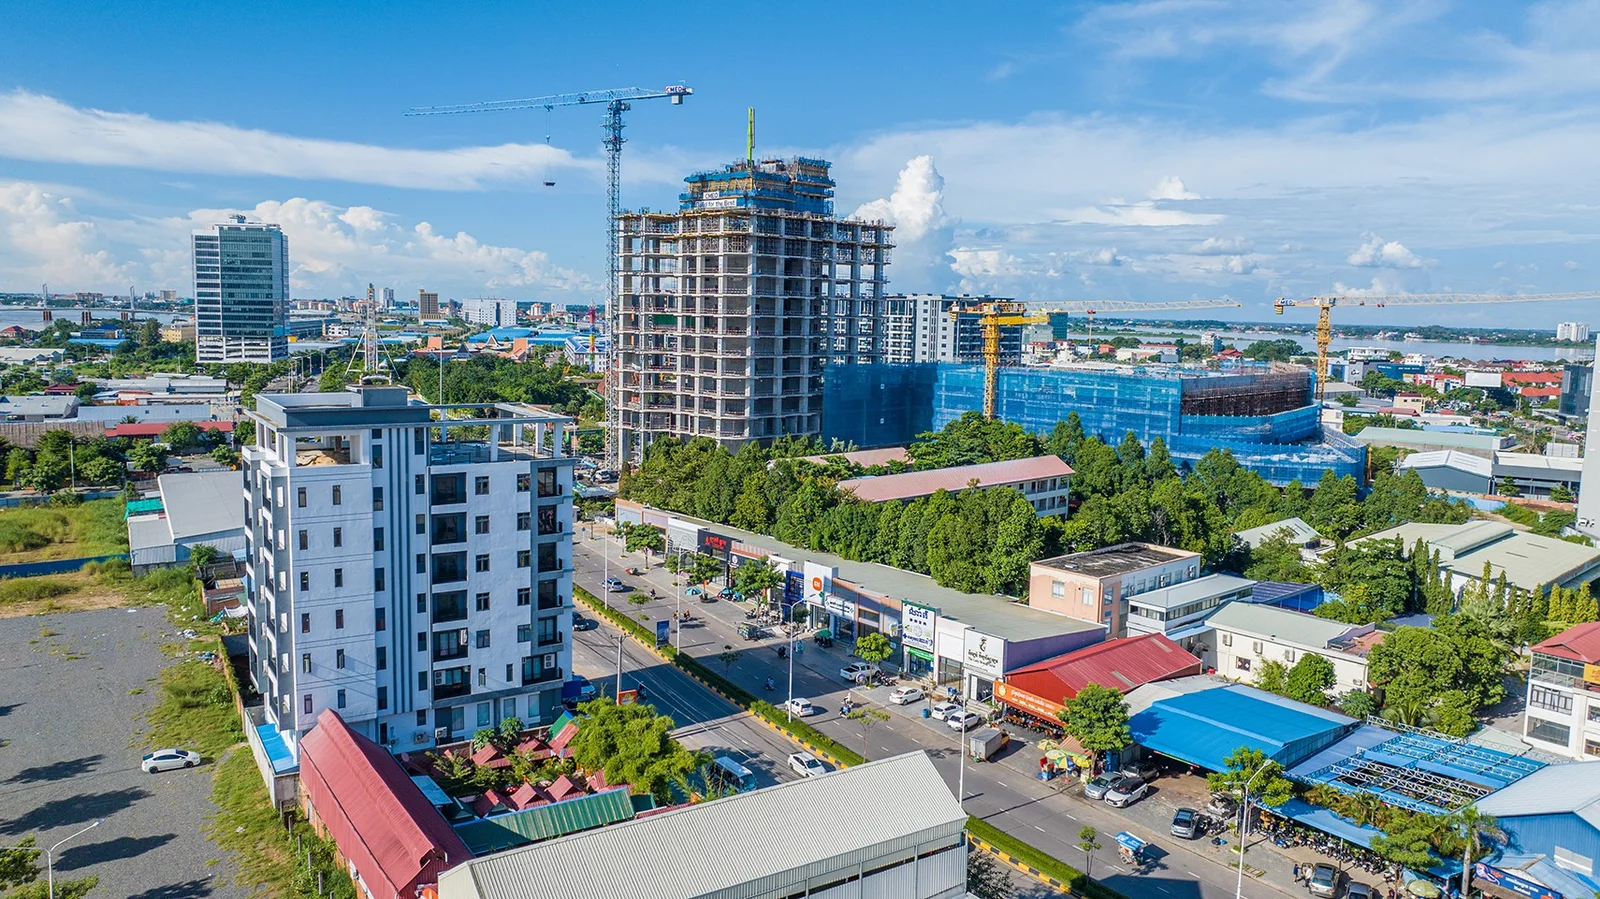
Quick answer: The Flatiron is Meridian International Holding’s completed 41-storey tower in Daun Penh: 272 freehold strata offices (asks $250,000-$1.2M) plus 330 Citadines Apart’Hotel units under The Ascott Limited. Foreigners can hold both outright, same law as condos. The income math runs on Grade A rents of $28-40 per sqm against a 64%-occupancy office market. Covenant quality decides everything.
This is the only Wave-2 page that covers a whole product category as well as a building: strata offices a foreigner can hold freehold. The corpus’s office registry finally gets its owner address, and the verification format stays the same: verified, claimed, must-obtain.
What is the Flatiron and who builds it?
The Flatiron is Meridian International Holding’s completed 41-storey landmark on Street 102 in Srah Chak, Daun Penh, about 84,000 sqm of GFA split into 272 freehold strata offices and 330 Citadines Apart’Hotel units managed by The Ascott Limited. The developer’s third project, it is Phnom Penh’s clearest test of strata-office ownership.
| Fact | Verified position | Note |
|---|---|---|
| Developer | Meridian International Holding | Third project |
| Location | Street 102, Srah Chak, Daun Penh | CBD-adjacent, not Veal Vong as some listings state |
| Scale | 41 storeys, ~84,000 sqm GFA | Completed; construction from November 2018 |
| Offices | 272 freehold strata units | Sold to investors, title per unit |
| Hotel | 330 Citadines Apart’Hotel units | Operated by The Ascott Limited |
| Office asks | $250,000-$1.2M reported | Underwrite from rent, not from asks |
Our read of the Flatiron treats it as a case study before treating it as a listing, because the building settles a question that still surprises most foreign investors: Cambodia’s strata law is product-agnostic above the ground floor, and a completed tower has now sold 272 offices on exactly that basis. That precedent does more for a buyer than any brochure: it means the legal path is not theoretical, the co-ownership structure has operated across hundreds of commercial owners, and the strata-office exit, however negotiated, has real transaction history. The two-product stack is the second structural fact: offices and an Ascott-branded apart-hotel share one address but not one economics, and the building’s value to this corpus is precisely that it forces both analyses, corporate covenant income above, operator-pool income below: onto the same page, where their risks can be compared instead of blurred.
- The product category in full: Phnom Penh office investment guide.
- The district: Daun Penh area profile.
- The off-plan office comparison: Odom review.
- Commercial property, end to end: commercial investment guide.
- The legal machinery: foreign ownership and strata title.
Can foreigners hold strata offices and hotel units?
Foreign buyers can hold both products here freehold: strata co-ownership law allows foreign ownership of offices and hotel units above the ground floor, the same mechanism as condominiums, inside the 70% cap on total private-unit area. Most foreign investors do not know the law reaches this far, which is why the Flatiron’s 272 offices matter beyond one address.
| Ownership item | Position here | What to demand |
|---|---|---|
| Legal basis | Strata co-ownership, Sub-Decree 126 | Same law as residential strata |
| Products covered | Offices and hotel units alike | Above ground floor only |
| Foreign cap | 70% of total private-unit area | Dated ledger extract in sqm |
| Title | Individual strata title per unit | Land Office verification |
| Office-specific | Co-ownership rules on use, signage, hours | The commercial clauses, in writing |
| Hotel-specific | Management agreement binds the unit | Read it before the SPA, not after |
Our analysis of the ownership layer adds a commercial checklist on top of the standard one, and the additions are where office buyers get surprised. The base file is familiar: title copy, encumbrance search, quota extract in square metres, co-ownership regulations. The commercial layer starts there: the regulations’ use provisions decide what business a tenant may run, what signage it may hang and what hours the building supports, terms that determine which covenants you can actually sign; the service-charge regime for commercial floors runs $2 to $5 per sqm monthly and belongs inside every yield model; and for the hotel units, the Ascott management agreement is effectively part of the title, it binds successive owners, sets the income formula, and constrains resale, so it gets read with a lawyer before any deposit, with the same weight as the SPA itself. Every item is obtainable; a completed building has no excuse for missing paper.
- The legal baseline: can foreigners buy property in Cambodia.
- The cap, correctly: strata title for foreign buyers.
- Process discipline: due diligence step by step.
- Registration mechanics: strata co-ownership registration.
- Contract review: SPA review for foreign buyers.
What do the offices cost, and what do they rent for?
Office asks at the Flatiron run $250,000 to $1.2 million, and the income side is Grade A arithmetic: space rents at $28 to $40 per sqm monthly, with $2 to $5 service charges on top, and this market’s occupancy reads about 64% after years of heavy supply. The arithmetic works, and what a buyer pays for it is the risk of long voids between corporate tenants.
| Income input | Figure | Note |
|---|---|---|
| Ask range | $250,000-$1.2M | By floor and size |
| Grade A rent | $28-$40 per sqm per month | The registry’s top band |
| Grade B contrast | $18-$29 per sqm per month | What competing stock charges |
| Service charge | $2-$5 per sqm per month | On top of rent |
| Market occupancy | ~64%, vs ~90% pre-supply peak | Rents ~20% below 2019 |
| Market stock | ~1.3 million sqm forecast 2026 | 144,000+ sqm added in the year |
The methodology for a strata office is lease-first, and we tracked the market’s supply data precisely because it turns the headline yield honest. A 100 sqm unit bought at $350,000 and let at $32 per sqm grosses $3,200 a month, an 11% gross that explains every office brochure ever printed. The same unit’s truth: Phnom Penh’s office stock grew from about 500,000 sqm in 2019 to over a million by 2023 and toward 1.3 million in 2026, occupancy across the market reads near 64%, and asking rents sit roughly 20% below 2019, so the realistic model is not 12 months of rent but a cycle: months of void while a covenant is found, a fit-out period, then a 2-3 year corporate term that repays the wait. Across a full cycle a well-let Flatiron office still out-earns a condo per dollar; an unlet one costs its service charges while earning nothing, which makes the tenant network, not the tower, the asset being underwritten.
- The market data in full: office investment guide.
- Commercial underwriting: commercial property guide.
- Negotiating the ask: negotiation guide.
- Costs of closing: closing costs guide.
- Income tax treatment: rental income tax.
How do the Ascott-run hotel units actually pay?
The Flatiron’s 330 hotel units sit inside the same 84,000 sqm tower as its offices, run as a Citadines Apart’Hotel under The Ascott Limited, which means foreign buyers’ income arrives through an operator’s rent pool, with no tenant’s lease behind it. The structure requires the corpus’s guarantee-scheme discipline: read the pool formula, fee stack and exit clauses first.
| Structure item | How it works | What to verify |
|---|---|---|
| Operator | The Ascott Limited (Citadines brand) | Term and renewal of the agreement |
| Income | Distribution from operating results | The exact formula, in the contract |
| Fees | Operator, brand, marketing, FF&E reserves | The full stack, line by line |
| Weak quarters | Distributions can fall or pause | What the floor is, if any |
| Owner use | Typically limited nights per year | The precise entitlement |
| Exit | Sale carries the agreement with it | Assignment and consent clauses |
Insider tip: the single question that cuts through every operator-structure pitch is “show me the trailing distributions, per unit, for the last eight quarters”, a completed, operating apart-hotel has that table, and the red flag is any seller or agent who substitutes projections for it. Ascott is a genuine global operator and Citadines a real brand, which removes the fly-by-night risk that sank Cambodia’s guarantee-scheme era, but brand quality does not change the structure’s nature: owners hold the downside of occupancy, the operator’s fee stack sits above distributions, and a unit’s resale market consists only of buyers willing to inherit the agreement. Priced honestly, actual trailing distributions against the ask, a branded hotel unit can be a legitimate hands-off hold: at, say, $200 of net monthly distribution on a $60,000 unit, the real yield is 4% and the decision is rational either way. Priced on projections of 8% to 10%, it repeats the exact mistake the corpus’s rent-guarantee warning was written to prevent, with better wallpaper.
- The cautionary framework: rent guarantee schemes warning.
- The serviced product economics: serviced apartments investment.
- Hotel-sector context: hotel and guesthouse investment.
- Exit thinking now: exit strategy guide.
- The contract that rules it all: SPA review guide.
Weighing a Flatiron office or Citadines unit? We will model the covenant math against real market occupancy, read the management agreement's fee stack, and verify title and quota, before you respond to an ask.
Get the commercial analysisHow does it compare with buying a condo for income?
An office against a condo for income is a covenant trade: companies sign multi-year terms at $28 to $40 per sqm and fit out at their own cost, while a one-bedroom lets tenants at $650 to $1,350 in BKK1. The office pays more per sqm and voids longer; the condo churns faster and exits easier for foreign buyers.
| Dimension | Strata office | Condo |
|---|---|---|
| Rent per sqm | $28-$40/month Grade A | Effectively lower per sqm |
| Lease length | 2-3+ year corporate terms | 6-12 months typical |
| Void profile | Long searches, ~64% market occupancy | ~15% vacancy, faster refill |
| Fit-out | Tenant funds it | Owner furnishes |
| Exit | Negotiated, thin buyer pool | Listed, deeper pool |
| Management burden | Low once let | Continuous |
Our underwriting of the choice always ends at the same fork, and the buyer scenario decides it better than the yield table does. The office suits capital with holding power and access to tenants: a buyer whose business network can produce a covenant, or who buys premises for their own company, the strongest case of all, converts the market’s 64% occupancy from threat into negotiating leverage, pays fit-out with nothing, and holds an income stream residential cannot match per dollar. The condo suits capital that needs liquidity and forgiveness: churn is annoying but survivable, voids are measured in weeks not quarters, and the exit is a listing rather than a search for the one buyer who wants a 100 sqm office with your tenant’s lease attached. The mistake this page exists to prevent is buying the office’s headline rate with the condo’s patience: that buyer ends up funding service charges on empty Grade A space while a one-bedroom would have been quietly compounding.
- Both machines, priced: office investment guide vs rental yield guide.
- The off-plan office alternative: Odom Tower.
- Residential benchmarks: best condos to buy 2026.
- Own-use premises: commercial investment guide.
- District context: Daun Penh profile.
What we could verify on a completed landmark
| Claim | Classification | Evidence |
|---|---|---|
| Developer: Meridian International Holding, third project | Verified | Developer and portal sources |
| 41 storeys, ~84,000 sqm GFA, Street 102 Srah Chak | Verified | Consistent across sources; corrects “Veal Vong” errors |
| 272 strata offices + 330 Citadines units | Verified | Project documentation |
| Ascott management of hotel component | Verified | Operator’s own listings |
| Construction from November 2018; completed | Verified | Standing, operating |
| Office asks $250,000-$1.2M | Reported | Agency-side range, asks, not closings |
| Trailing hotel distributions | Must obtain | Eight quarters, per unit, from the operator |
| Quota ledger, office closings, management agreement | Must obtain | Dated documents before any deposit |
The verified rows make the Flatiron the reference building for a whole product category: nothing about foreign strata-office ownership here is theoretical. The must-obtain rows are where individual deals succeed or fail, actual closed office prices against reported asks, actual distributions against hotel projections, actual clauses against brochure summaries. A landmark this documented rewards the buyer who insists the paperwork match the architecture.
The distinction between the two product stacks deserves a final paragraph, because it is where this building’s search results mislead most. Listings present “the Flatiron” as one investment with one price range, but an office buyer and a hotel-unit buyer at the same address are entering different contracts, different income machines, and different exits: the office buyer becomes a landlord with a covenant to find; the hotel-unit buyer becomes a silent partner in an operating business they do not control. Both are legitimate; both are foreign-eligible; and the building’s genuine achievement is making both real at strata scale in a completed tower. But the diligence files barely overlap, and a buyer who has assembled the wrong file has verified nothing. Decide the product first, landlord or partner, and let that decision drive which documents this page’s checklist actually means for you, whatever the floor plan brochure emphasises.
Advantages and disadvantages
For the purchase: the clearest completed proof that foreigners can hold commercial strata freehold; Grade A income density no residential product matches per sqm; corporate covenants that fund their own fit-out; an Ascott-branded operator on the hotel side rather than an unknown; and Daun Penh permanence under it all.
Against it: a citywide office market at ~64% occupancy with rents ~20% below 2019 and 144,000+ sqm of fresh supply in a single year; voids measured in quarters; a negotiated, thin exit for offices and an agreement-bound one for hotel units; fee stacks that stand between hotel owners and gross revenue; and asks whose distance from closed prices is itself a must-obtain fact.
Buyer scenarios and decision framework
A business owner buying premises is the strongest buyer in the building, own-use converts every market risk into cost control, and freehold beats a decade of rent reviews. An investor with a tenant network can underwrite the covenant game honestly and should negotiate hard off the 64% figure. A hands-off income buyer belongs in the hotel component only after reading trailing distributions, or in a condo instead, if the fee stack offends. And a liquidity-sensitive buyer should recognise the exit profile before entry: commercial strata rewards patience and punishes urgency, in both directions of the transaction.
Closing verification checklist
Before any commitment: verify title, encumbrance and the 70% quota extract at the Land Office; obtain closed office comparables from inside the building, 272 units of history exist; read the co-ownership regulations’ commercial clauses and the full service-charge regime; for hotel units, obtain the management agreement and eight quarters of per-unit distributions before pricing anything; model the office at cycle-honest occupancy that counts the months before a lease is signed; and time the transfer against the 2026-12-31 duty window with the 20% capital gains regime from 2027 in the exit model. Where the building’s own history can answer a question, closed prices, real distributions, actual tenancy terms, never accept a projection in its place. A completed landmark has already generated every document this list names: the only question is whether you read them before or after the wire.
Frequently Asked Questions
A completed 41-storey landmark on Street 102 in Srah Chak, Daun Penh, Meridian International Holding's third project, about 84,000 sqm of GFA divided into 272 freehold strata office units and 330 Citadines Apart'Hotel units managed by The Ascott Limited. Construction ran from November 2018; the tower is complete and operating.
Yes: the same strata co-ownership law that covers condominiums allows foreign freehold of office and hotel units above the ground floor, inside the 70% cap on total private-unit area. The Flatiron is the clearest completed example: 272 strata offices sold to investors, title issued per unit.
Reported asks run $250,000 to $1.2 million depending on floor and size. Underwrite from the rent side: Grade A Phnom Penh office space rents at $28 to $40 per sqm per month with $2 to $5 service charges on top, in a market whose occupancy reads about 64% after years of new supply. The covenant, not the view, carries the value.
Through an operator structure, not a lease: Citadines' rooms earn nightly revenue, and owners receive distributions per the management agreement's formula after operating costs and fees. The brand is genuine; the discipline is reading the pool formula, the full fee stack, what happens in weak quarters, and the exit-and-resale clauses before committing.
Different machines. The office pays more per sqm on multi-year corporate terms and the tenant funds fit-out, but voids run long in a 64%-occupancy market and resale is negotiated, not listed. The condo earns less per sqm, churns faster, and exits into a deeper buyer pool. Match the product to your holding power, not to the headline rate.
It is the best-documented way to hold commercial Phnom Penh at strata scale: completed, branded, legally clean for foreigners. The risks are market-wide, not building-specific, office oversupply, operator-structure opacity on the hotel side. Buyers with tenant networks or long horizons fit; buyers needing quick liquidity generally do not.
Get a Cambodia property shortlist
Share your budget, target district (BKK1, Koh Pich, Koh Norea, Siem Reap), and goal. We reply within one business day with matched stock and next steps.