Phnom Penh Rental Yield Guide 2026: Realistic Net Returns
Phnom Penh rental yield 2026: why 12-15% gross is marketing only, how to model net yield after vacancy, fees and tax, plus real BKK1 and BKK3 rent bands.
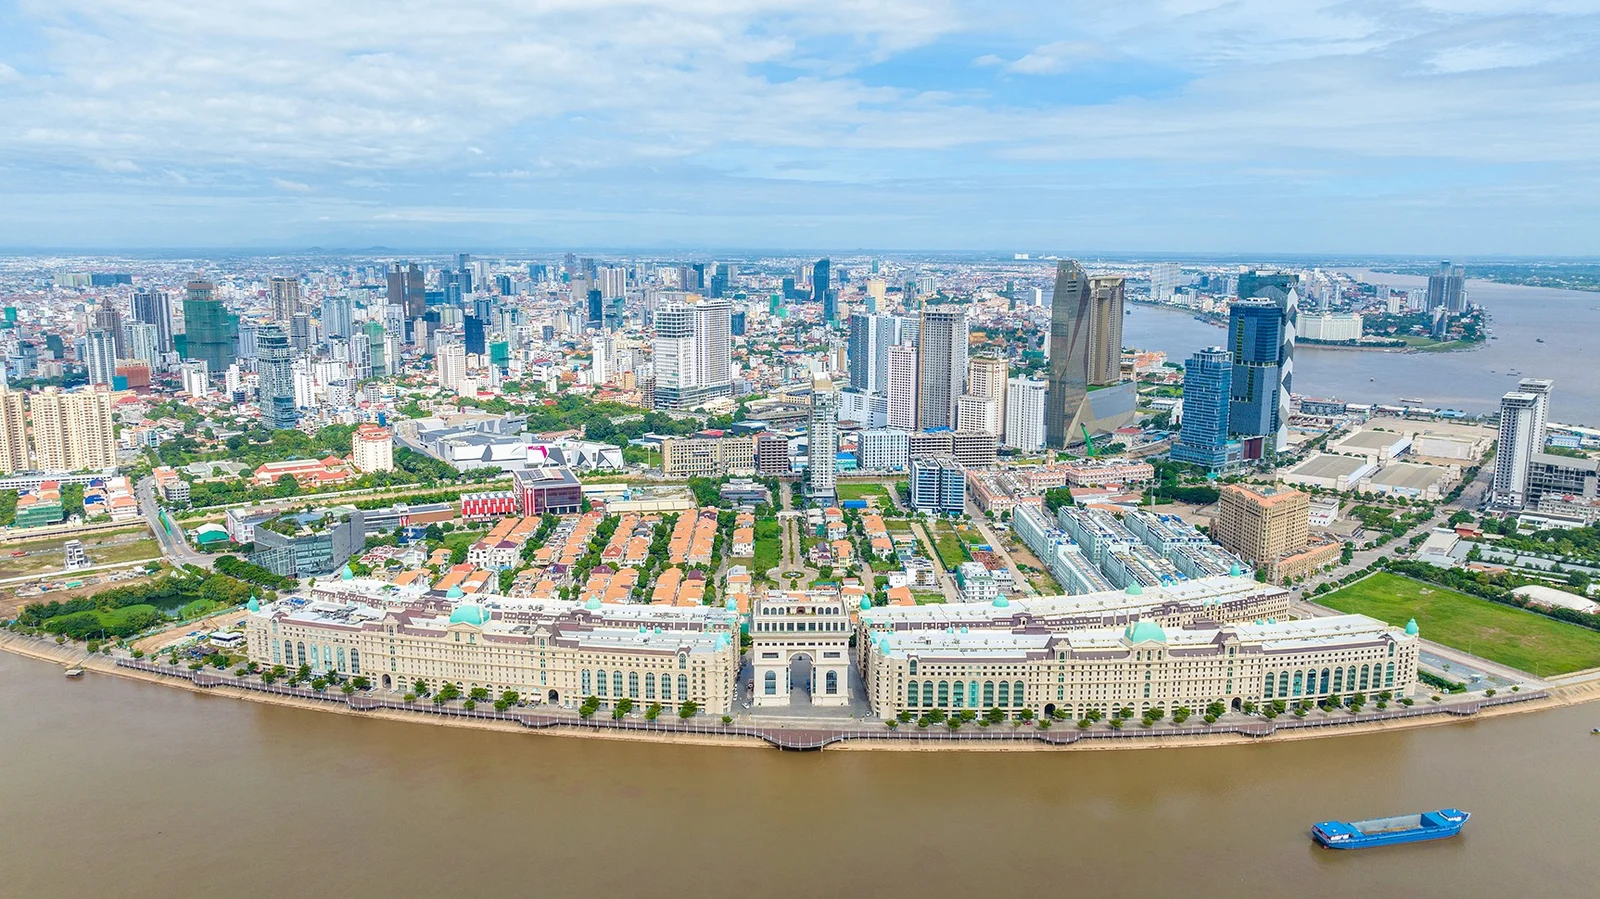
Quick answer: Realistic Phnom Penh net rental yield in 2026 sits around 4% to 6% after vacancy, management, sinking fund and tax, even where developers advertise 12% to 15% gross. Foreign buyers hold strata co-ownership above ground floor within a 70% per building quota, condo stock is 76,000 to 80,000 units, and average pricing is near $1,800 per sqm. Treat any gross headline above 8% as marketing only with no guarantees.
Invest Cambodia Editorial tracks Phnom Penh strata condos for foreign buyers with a focus on what units actually rent for, not what brochures promise. This guide separates marketing gross yield from the net cash flow you can bank, using 2026 supply, fee and tax inputs and verified district rent bands.
For portfolio context read Cambodia Property Investment Guide 2026, Can Foreigners Buy Property Cambodia, Due Diligence Process Cambodia Step By Step, Cambodia Property Taxes Fees 2026, and Off Plan Property Cambodia Guide.
What net rental yield is realistic in Phnom Penh in 2026?
Net yield is the only number that pays your bills. Gross yield divides annual asking rent by purchase price and stops there. The difference between the two in Phnom Penh is wide because the market carries genuine vacancy risk from 76,000 to 80,000 condo units, management is essential for absentee foreign owners, and furnishing wears down faster in short-let use. Anchor your decision to net, and treat gross as a marketing label.
| 2026 metric | Indicative value | Buyer use |
|---|---|---|
| Phnom Penh avg price | $1,800 per sqm | Baseline vs district premium |
| Foreign quota cap | 70% per building | Above ground floor only |
| Banking NPL ratio | 8.9% | Developer completion risk |
| Stamp duty window | Through 31 December 2026 | Registration timing |
Why are 12 to 15% gross yield claims marketing only?
Developers and resellers quote gross because it is the largest defensible figure. A unit bought at $60,000 that asks $600 a month shows a 12% gross headline on paper. In reality, that owner faces one to two months of vacancy, a management fee of 8% to 12% of collected rent, a monthly sinking fund and service charge, furnishing replacement every few years, and rental income tax. Each line trims the headline. The honest result for that same unit is closer to a 5% net yield, and lower if the building sits in an oversupplied cluster where rents are being discounted to fill vacancies. Demand the rent comps, fee schedule and occupancy history behind any gross promise.
How do you calculate net rental yield in Phnom Penh?
The table below shows how a typical $60,000 BKK3 one-bedroom moves from a marketed gross figure to a bankable net figure. The inputs are conservative and reflect 2026 conditions. The full deduction stack, including rental income tax at 10% resident or 14% non-resident and the order in which the deductions apply, is set out in net versus gross yield on Cambodian condos.
| Line item | Annual amount | Effect on yield |
|---|---|---|
| Asking rent at full occupancy | $7,200 | 12.0% gross headline |
| Vacancy allowance (1.5 months) | minus $900 | Collected rent falls |
| Management fee (10% of rent) | minus $630 | Absentee owner essential |
| Service charge and sinking fund | minus $480 | Confirm before deposit |
| Maintenance and furnishing wear | minus $600 | Budget every year |
| Rental income tax and admin | minus $700 | Net of withholding |
| Net annual income | $3,890 | 6.5% net on $60,000 |
The same exercise on a premium $150,000 Koh Pich unit usually nets lower, near 4% to 5%, because end-user rent does not scale with the higher entry price. The discipline is identical: collected rent in, every cost out, divide by full acquisition cost.
What rent do BKK1, BKK3 and Tonle Bassac condos actually achieve?
Furnished one-bedroom units in central Phnom Penh achieve roughly $350 to $850 a month in 2026, with two-bedrooms at $600 to $1,600 depending on district and tenant profile. The bands below are indicative and should be checked against live signed comps in the specific building, because building-level variance inside one district is wider than the gap between districts.
| District | One-bedroom rent | Two-bedroom rent | Tenant profile |
|---|---|---|---|
| BKK1 | $450 to $750 | $800 to $1,400 | Embassy, NGO, senior expat |
| BKK3 | $350 to $550 | $600 to $950 | Young expat, remote worker |
| Tonle Bassac | $500 to $850 | $900 to $1,600 | Riverside, corporate lease |
| Toul Kork | $350 to $600 | $650 to $1,000 | Family, education-linked |
| Toul Tom Poung | $400 to $650 | $700 to $1,100 | Boutique, lifestyle expat |
Read the district detail in BKK1 Phnom Penh, BKK3 Phnom Penh and Tonle Bassac before you fix an assumption. The cross-market call between the two strongest investor districts is set out in BKK1 VS BKK3 Investment.
How does the 76,000 unit supply affect rents?
Oversupply does not destroy yield, but it changes how you defend it. In a tight market a landlord can hold rent and wait. In Phnom Penh you re-let on price, which is why vacancy must be modelled at one to two months rather than the optimistic two weeks a brochure implies. Buildings with strong management, distinctive amenities and a defensible address resist discounting better than commodity towers. This is the single biggest reason a generic 12% gross promise collapses to a 5% net reality.
What occupancy and vacancy should you model for Phnom Penh?
Vacancy is the assumption most owners get wrong. A unit that sits empty for two months has already lost 16% of its annual rent before any other cost. Long corporate leases in BKK1 and Tonle Bassac reduce churn but pay slightly below short-let asking rates. Short lets chase higher nightly rates but expose you to seasonality, platform fees and faster furnishing wear. Pick one strategy, model its real occupancy, and do not blend the best of both into a single optimistic line.
Which districts give the best risk-adjusted net yield?
| District | Gross signal | Risk-adjusted net | Why |
|---|---|---|---|
| BKK1 | Moderate | Strong | Stable expat demand, faster re-let |
| BKK3 | High headline | Moderate | Lower rent, heavy supply |
| Tonle Bassac | Moderate | Strong | Corporate and riverside premium |
| Koh Pich | Lower | Moderate | End-user brand, thinner rent pool |
| Koh Norea | Speculative | Watch | Amenities still maturing |
A high gross figure in an oversupplied cluster is not a bargain if it comes with three months of vacancy and annual rent cuts. Weight your shortlist toward districts where you can defend the rent, then verify the specific building. District-level yield bands with entry prices per sqm and tenant profiles are set out in the Phnom Penh district rental yield comparison, which owns that table.
Three numbers separate a risk-adjusted winner from a headline one, and our underwriting weighs them in this order:
- Void length. Each void month on a $130,000 unit removes about $750 of rent, roughly 60 to 90 basis points of net yield.
- Rent defensibility. Central districts hold rent through supply cycles; outer districts discount 10% to 15% to fill.
- Exit depth. A local-only buyer pool at resale narrows your exit regardless of the yield you collected.
How do Megakim entry projects compare on yield?
| Project tier | Indicative entry | Payment structure | Yield reality check |
|---|---|---|---|
| Megakim entry | From about $40,000 | 20% down, 40-month plan | Verify rent comps and quota |
| BKK3 mid-market | $50,000 to $90,000 | Varies by launch | Model heavy local supply |
| BKK1 resale | $90,000 plus | Cash or limited finance | Strongest tenant pool |
| Koh Pich premium | $120,000 plus | Developer terms | Brand premium, lower gross |
A lower entry price flatters gross yield because the denominator shrinks, but it often pairs with weaker tenant demand and a thinner resale pool. Project-level detail sits in Time Square Ocean View, Square Castle and Diamond Bay Garden. The developer track-record question is covered in Developer Due Diligence Red Flags Cambodia.
What does the 70% foreign quota mean for rental investors?
If a building is already near its 70% foreign ceiling, your future resale pool narrows to Cambodian buyers, who price differently and may value the unit lower. Always request written confirmation of remaining foreign quota in the building registry before paying a deposit, and treat the strata title path as separate from any landed product. The ownership mechanics are explained in Can Foreigners Buy Property Cambodia and Foreign Ownership Strata Title Cambodia.
How do taxes, stamp duty and fees change your net return?
| Cost or tax | Indicative level | When it hits |
|---|---|---|
| Stamp duty | Incentive to 31 Dec 2026 | At purchase |
| Legal review | $800 to $2,500 | At purchase |
| Furnishing | $5,000 to $15,000 | Before first tenant |
| Management fee | 8% to 12% of rent | Monthly |
| Service and sinking fund | $40 to $80 per month | Monthly |
| Rental income tax | Per Cambodian rules | On income |
| Capital gains tax | Deferred to 1 Jan 2027 | At exit |
The full breakdown and current rates are maintained in Cambodia Property Taxes Fees 2026. Confirm the live stamp duty position with a Cambodian lawyer before you rely on the incentive in your model.
Want the yield modelled on your actual unit, after the 14% charge, management, service charge and a realistic void?
Model your net yieldWhat are the advantages and disadvantages of Phnom Penh rental property?
Phnom Penh rental property offers USD-priced entry, accessible payment plans and ASEAN demographic growth, balanced against oversupply, thin resale liquidity and inflated gross marketing. The advantages favour patient cash buyers; the disadvantages punish anyone who underwrites on the brochure.
| Advantages | Disadvantages |
|---|---|
| USD-priced entry from about $40,000 | 76,000 to 80,000 units cap rent growth |
| Stamp duty incentive lowers 2026 cost | Realistic net is 4% to 6%, not 12% to 15% |
| Strata path for above-ground units | 70% quota can fill in popular towers |
| Young, urbanising tenant base | Resale liquidity thinner than Bangkok |
| Megakim 20% down, 40-month plan | 8.9% banking NPL tightens financing |
| Long corporate leases in BKK1 | Vacancy of 1 to 2 months is normal |
What are the red flags and risks when underwriting yield?
- Gross inflation: Any gross yield above 8% needs rent comps, a fee schedule, vacancy history and furnishing amortisation in writing.
- Quota full: Request the building foreign quota ledger; a near-full ceiling narrows your resale exit.
- Developer delay: Cross-check OCIC, Megakim, Chip Mong and Urbanland handover history against current construction photos.
- Banking stress: The 8.9% banking NPL ratio signals tighter developer financing; ask for escrow and construction progress proof on off-plan instalments.
- Tax timing: Capital gains tax deferred to 1 January 2027 may shift seller behaviour late in 2026; model your exit before buying for flip potential.
Insider tip: Ask the building manager for the actual collected-rent roll and current vacancy count, not the developer rental projection. Visit the unit stack twice on a weekday, because boulevard noise in BKK1 and active construction near Koh Norea change how a tenant values the same floor.
Which buyer scenarios fit Phnom Penh rental investment?
Phnom Penh rental investment fits patient USD cash buyers and instalment buyers who accept thin liquidity, more than it fits short-hold flippers who need fast resale. Match the scenario to your hold period and your tolerance for vacancy.
| Profile | Budget | Best fit | Starting point |
|---|---|---|---|
| Entry investor | Under $50,000 | Megakim instalment unit | Off Plan Property Cambodia Guide |
| Yield-focused | $50,000 to $100,000 | BKK3 or outer BKK1 | BKK1 VS BKK3 Investment |
| Stability-focused | $90,000 to $200,000 | BKK1 or Tonle Bassac | BKK1 Phnom Penh |
| Regional comparison | Any | Cambodia vs neighbours | Cambodia VS Thailand Property Investment |
Scenario A: An entry buyer with under $50,000 uses a Megakim 20% down, 40-month plan, accepts construction and resale liquidity risk, and underwrites a 5% net with two months of vacancy.
Scenario B: A yield-focused buyer compares BKK3 launch gross against BKK1 resale net, and chooses BKK1 because the tenant pool re-lets faster despite a higher entry price near $1,800 per sqm.
Scenario C: A stability-focused buyer targets Tonle Bassac or BKK1 for corporate leases, accepts a lower 4% to 5% net, and prioritises re-let speed and resale depth over headline gross.
How does Phnom Penh net yield compare to Bangkok and the region?
The regional decision is not only about yield. Bangkok offers deeper liquidity and a larger tenant market; Phnom Penh offers a lower ticket, USD denomination and a younger demographic curve. For a side-by-side on entry price, title path, liquidity and who each market suits, read Cambodia VS Thailand Property Investment and the focused comparison in Cambodia VS Thailand Property.
How do short lets compare to long leases for net yield?
The trade-off is occupancy stability versus headline rate. A short-let unit in a tourist-adjacent pocket might advertise a strong nightly rate, but seasonality, weekday gaps and platform commission of 15% or more erode the gross fast. A long lease pays slightly below short-let asking, yet it removes re-let friction, cuts cleaning turnover and protects furnishing, which is the line most owners under-budget. In an oversupplied market, the tenant you keep for two years is worth more than the higher nightly rate you advertise and cannot fill. Model both strategies separately, with their own occupancy and cost lines, then choose the one your management partner can actually execute.
| Strategy | Gross signal | Net reality | Best for |
|---|---|---|---|
| Long corporate lease | Moderate | Strong, stable | Absentee owners, BKK1 |
| Standard 12-month lease | Moderate | Solid | Most foreign buyers |
| Short let | High headline | Volatile, lower net | Hands-on, tourist pockets |
What furnishing and fit-out level do Phnom Penh tenants expect?
The furnishing standard sets your tenant band. A clean, neutral, fully-equipped one-bedroom with reliable air conditioning, a working kitchen and fast internet competes for the stable corporate tenant. A cheap fit-out chases price-sensitive renters who churn faster and negotiate harder. Furnishing also wears, especially in short-let use, so amortise replacement across roughly five years and put that line in your model. A landlord who furnishes once and never refreshes watches achievable rent drift below the building average within three to four years. The cost detail and other acquisition lines are tracked in Cambodia Property Taxes Fees 2026.
How do you build a defensible rent comp file?
Asking prices mislead because oversupplied buildings list 10% to 20% above what tenants sign. Developer rental projections mislead because they assume their own best case. The building manager and an independent local agent are your best sources for collected-rent data. Match like for like: a high-floor furnished unit with a river view is not a comp for a low-floor unit facing a light well. Once you have the median signed rent, apply your vacancy and cost lines on top. This single discipline is what separates a 6% net that holds from a 12% gross that evaporates. The wider verification workflow sits in Due Diligence Process Cambodia Step By Step.
What financing options exist for foreign rental buyers?
Where local bank finance is offered to foreigners, rates and terms are tighter than in mature markets, and the 8.9% banking NPL ratio signals lenders are cautious. Treat any financing cost as a deduction in your net yield calculation, because leverage that costs more than your net yield erodes returns rather than amplifying them. A developer instalment plan is effectively interest-bearing through the price, so compare the cash price against the plan price before assuming the plan is free. For buyers weighing instalment off-plan against a completed resale, the structural trade-offs are covered in Buy New VS Resale Cambodia.
How do you stress-test a Phnom Penh yield before you buy?
A useful frame is the base, downside and stretch model. The base case uses your median signed-rent comp, 1.5 months vacancy and a 10% management fee. The downside case adds a month of vacancy, trims rent 10% to reflect cluster discounting, and assumes a furnishing replacement year. The stretch case is a long corporate lease at full occupancy. If you can only make the numbers work in the stretch case, you are buying the brochure, not the building. Invest Cambodia Editorial underwrites every Phnom Penh unit on the downside case first, because a 76,000 to 80,000 unit market with 3% to 4% annual absorption punishes optimistic assumptions, and the gap between a 12% gross promise and a 4% to 6% net reality is exactly where most foreign buyers lose money. Hold your offer to the number that survives the downside.
| Case | Vacancy | Rent vs comp | Net yield outcome |
|---|---|---|---|
| Base | 1.5 months | At median | 4% to 6% |
| Downside | 3 months | Minus 10% | 2% to 4% |
| Stretch | Near zero | Long corporate lease | 6% to 7% |
The discipline above pairs with the wider buyer playbook in Cambodia Property Investment Guide 2026, which sets the strategy before you reach the spreadsheet.
Closing verification checklist
Before you transfer funds, confirm remaining foreign quota in writing, validate the strata co-ownership template with a Cambodia lawyer, model net yield with one to two months of vacancy and a verified fee schedule, archive six months of signed lease comps for the building, and stress-test your exit against the capital gains tax change from 1 January 2027. Use Due Diligence Process Cambodia Step By Step as your transfer-day checklist.
Frequently Asked Questions
Most foreign owners realistically net 4% to 6% after vacancy, management, sinking fund and maintenance, even when the brochure quotes 12% to 15% gross. Model the gap line by line before you commit a deposit.
Headline gross figures ignore vacancy, fees, furnishing wear and tax. They are marketing only with no guarantees. A 12% to 15% gross claim typically lands near 4% to 6% net once real costs are deducted.
Well-located BKK1 one-bedroom units commonly lease at roughly $450 to $750 per month in 2026 depending on building age, amenities and furnishing. Verify recent signed leases, not asking prices, before underwriting.
Model 1 to 2 months of vacancy per year. With 76,000 to 80,000 condo units and 3% to 4% annual absorption, tenant churn is real and re-letting can take weeks in oversupplied clusters.
Rental income tax, a small annual immovable property tax and management fees all reduce net yield. The stamp duty incentive runs through 31 December 2026 and capital gains tax is deferred to 1 January 2027, which mainly affect acquisition and exit, not monthly cash flow.
realestate.com.kh data shows roughly 9% Polish buyer share, 9.6% Russian buyer share and 7.4% French buyer share among active foreign buyers, while tenant demand concentrates in BKK1, BKK3 and Tonle Bassac.
Get a Cambodia property shortlist
Share your budget, target district (BKK1, Koh Pich, Koh Norea, Siem Reap), and goal. We reply within one business day with matched stock and next steps.