Cambodia Condo Market Q2 2026: Supply and Absorption
Phnom Penh condo market Q2 2026 update: 76k to 80k units in stock, 3% to 4% absorption, average $1,800 per sqm, and what it means for buyers.
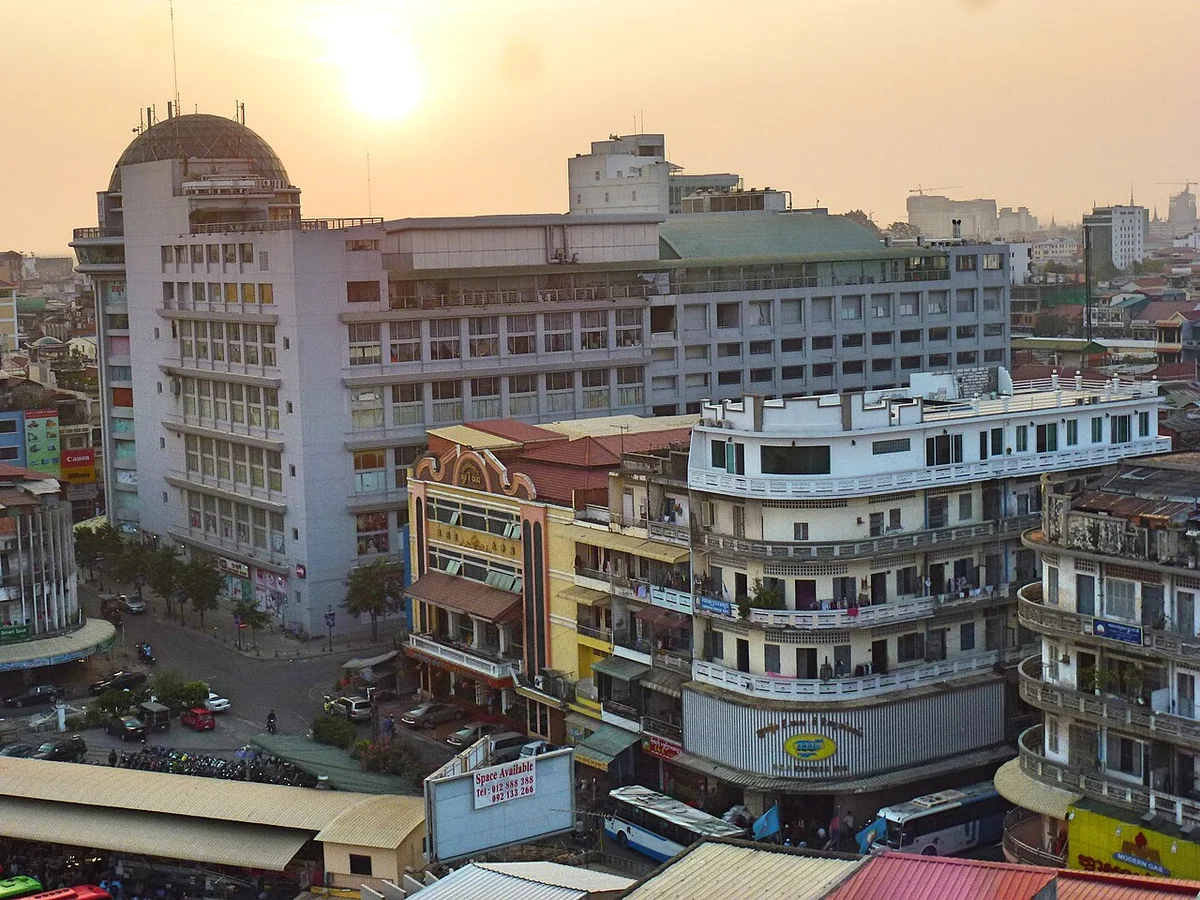
Quick answer: Phnom Penh entered Q2 2026 with roughly 76,000 to 80,000 condo units, annual absorption near 3% to 4%, and a blended average near $1,800 per sqm. Buyers should treat the city as oversupplied but bifurcated: negotiate hard on mid-market stock while verifying completion on discounted launches in BKK3 and Koh Norea.
Phnom Penh’s condo market in Q2 2026 is not a single price chart. It is two markets sharing one skyline: compact entry units marketed to overseas buyers on long instalment plans, and premium riverfront towers on Koh Pich that still command multiples of the citywide average. Between them sits a large middle inventory that absorbs slowly, which is why headline averages near $1,800 per sqm can mislead both bargain hunters and luxury shoppers.
Supply and absorption matter more than the last launch discount. Many towers compete for the same expat pool in BKK1, Tonle Bassac, and Toul Kork. Start with Best Areas Invest Phnom Penh 2026 for district differences.
How much stock sits on the market?
| Segment | Typical location | Q2 2026 signal |
|---|---|---|
| Entry compact | BKK3, Ta Khmau fringe | High launch volume, instalment plans |
| Mid family | Toul Kork, Sen Sok | Discounting on resale |
| Premium river | Koh Pich, Tonle Bassac | Price resilience, slower turnover |
| Airport corridor | Techo east | Speculative, amenity-dependent |
Banking NPL near 8.9% tightens developer credit on weaker names. That favours finished inventory over blind off-plan bets. Ly Peng Phat Central Tower sits in the urban core narrative, but foreign quota and district fundamentals decide rentability.
Why is absorption stuck near 3% to 4%?
Foreign buyer interest concentrates in entry tiers and trophy addresses, yet demand is not large enough to drain 80,000 units quickly. Use Phnom Penh Rental Yield Guide and Buy New VS Resale Cambodia for net yield models. Longer payment schedules and guaranteed-rent marketing need contract review, not blind trust.
| 2026 metric | Indicative value | Buyer use |
|---|---|---|
| Phnom Penh avg price | $1,800 per sqm | Baseline vs district premium |
| Foreign quota cap | 70% per building | Above ground floor only |
| Banking NPL ratio | 8.9% | Developer completion risk |
| Stamp duty window | Through 31 December 2026 | Registration timing |
What hides inside the $1,800 per sqm average?
| Price band | Example positioning | Buyer note |
|---|---|---|
| Under $1,200 per sqm | Outer ring, compact | Check tenant demand |
| $1,500 to $2,000 per sqm | Blended market average | Compare building age |
| $2,500 to $3,500+ per sqm | Koh Pich, core river | Liquidity slower but brand premium |
If a launch prices far below district peers, ask why. Foreign Ownership Strata Title Cambodia and quota checks matter at every price point.
Where are Q2 buyers finding value?
What the quarter changes for a buyer
A single quarter rarely changes a buying decision, and the useful reading is whether it confirms or breaks the trend a buyer is already underwriting. Against a stock of 76,000 to 80,000 condominium units absorbing only 3% to 4% a year, the structural picture moves slowly and the quarter is a data point rather than a signal.
| What to read | What it tells a buyer |
|---|---|
| Absorption rate | Whether supply is clearing at all |
| Occupancy, 75% to 80% citywide | What vacancy to model |
| Asking versus transacted price | How much negotiating room exists |
| New launches | Where competing supply will land |
| Banking NPL near 8.9% | Developer completion risk |
| Foreign quota movement by building | Your own exit pool |
Our underwriting treats absorption as the number that matters most in a quarterly reading, because price can hold while inventory builds and the gap between the two is where a buyer gets caught. A buyer scenario worth avoiding is treating a flat quarter as a floor: in a market absorbing 3% to 4% a year against this much stock, flat pricing with rising inventory is not stability.
- Absorption tells you more than price in an oversupplied market.
- A flat quarter with rising inventory is not a floor.
- The yearly picture sits in the 2026 market outlook.
- Occupancy data is in the occupancy guide.
- The investment verdict is in the 2026 verdict guide.
Want this quarter's numbers applied to one district and one building rather than the city as a whole?
Get a district readThe number the quarterly reports leave you to work out
Absorption of 3% to 4% a year against 76,000 to 80,000 standing units is roughly 2,400 to 3,200 units cleared annually. Divide the stock by the clearance and the standing inventory alone represents somewhere between 24 and 33 years of demand at the current rate, before a single unit of the pipeline completes. No quarterly report states it that way, and stating it that way changes what a buyer is looking at.
That arithmetic does not mean prices collapse, and the evidence says they have not: occupancy across districts sits at 75% to 80%, which is a functioning rental market, not an empty one. What the ratio means is that the marginal unit, the one still unsold in a tower that finished two years ago, has no scarcity behind it at all, and its price is set by how long its owner can wait rather than by demand. Scarcity in this market is local and specific: a particular layout on a particular floor in a building that people actually want to live in.
So the two questions worth asking about any Phnom Penh condo are not “is the market oversupplied”: it plainly is, but which side of that split the unit sits on, and who else is selling the same thing on the same street. A tower with forty unsold units competing with your resale is a different asset from an identical tower that sold out in 2021, and nothing in a citywide average distinguishes them.
Frequently Asked Questions
Market estimates place standing stock between 76,000 and 80,000 units across completed and actively marketed towers. New launches continue in Koh Pich, Koh Norea, and middle-ring districts, so inventory rises even as annual absorption stays near 3% to 4%.
Supply from the 2015 to 2022 build wave outpaced expat and local end-user growth. Foreign buyer interest remains visible, but concentrated in entry price tiers and premium riverfront stock, leaving mid-market towers competing on discounts and payment plans.
The figure blends affordable launches in BKK3 and Ta Khmau with premium Koh Pich and Tonle Bassac towers that trade far higher. Entry projects can start near $40,000 total for compact units, while prime riverfront stock can exceed $3,000 per sqm.
Buyers have negotiating power on payment terms, furnishings, and parking in oversupplied districts, but completion risk rises when developers discount aggressively. Favour finished units or escrow-backed off-plan from proven builders over pure price chasing.
The stamp duty exemption through 31 December 2026 lowers transfer cost on qualifying purchases, which can offset part of a modest discount. Pair the incentive with our stamp duty guide calculations and do not rush a risky off-plan deal to save tax alone.
Get a Cambodia property shortlist
Share your budget, target district (BKK1, Koh Pich, Koh Norea, Siem Reap), and goal. We reply within one business day with matched stock and next steps.